Independent insurance. A personal connection.Oregon City, Oregon · (503) 956-1640

INSURANCE FOR LARGE GROWER OPERATIONS

Built around the scale
of your operation.

A larger operation needs more than a basic farm-policy conversation. We review the structures, equipment, inventories and business activities across your locations.

Let’s talk about your coverage
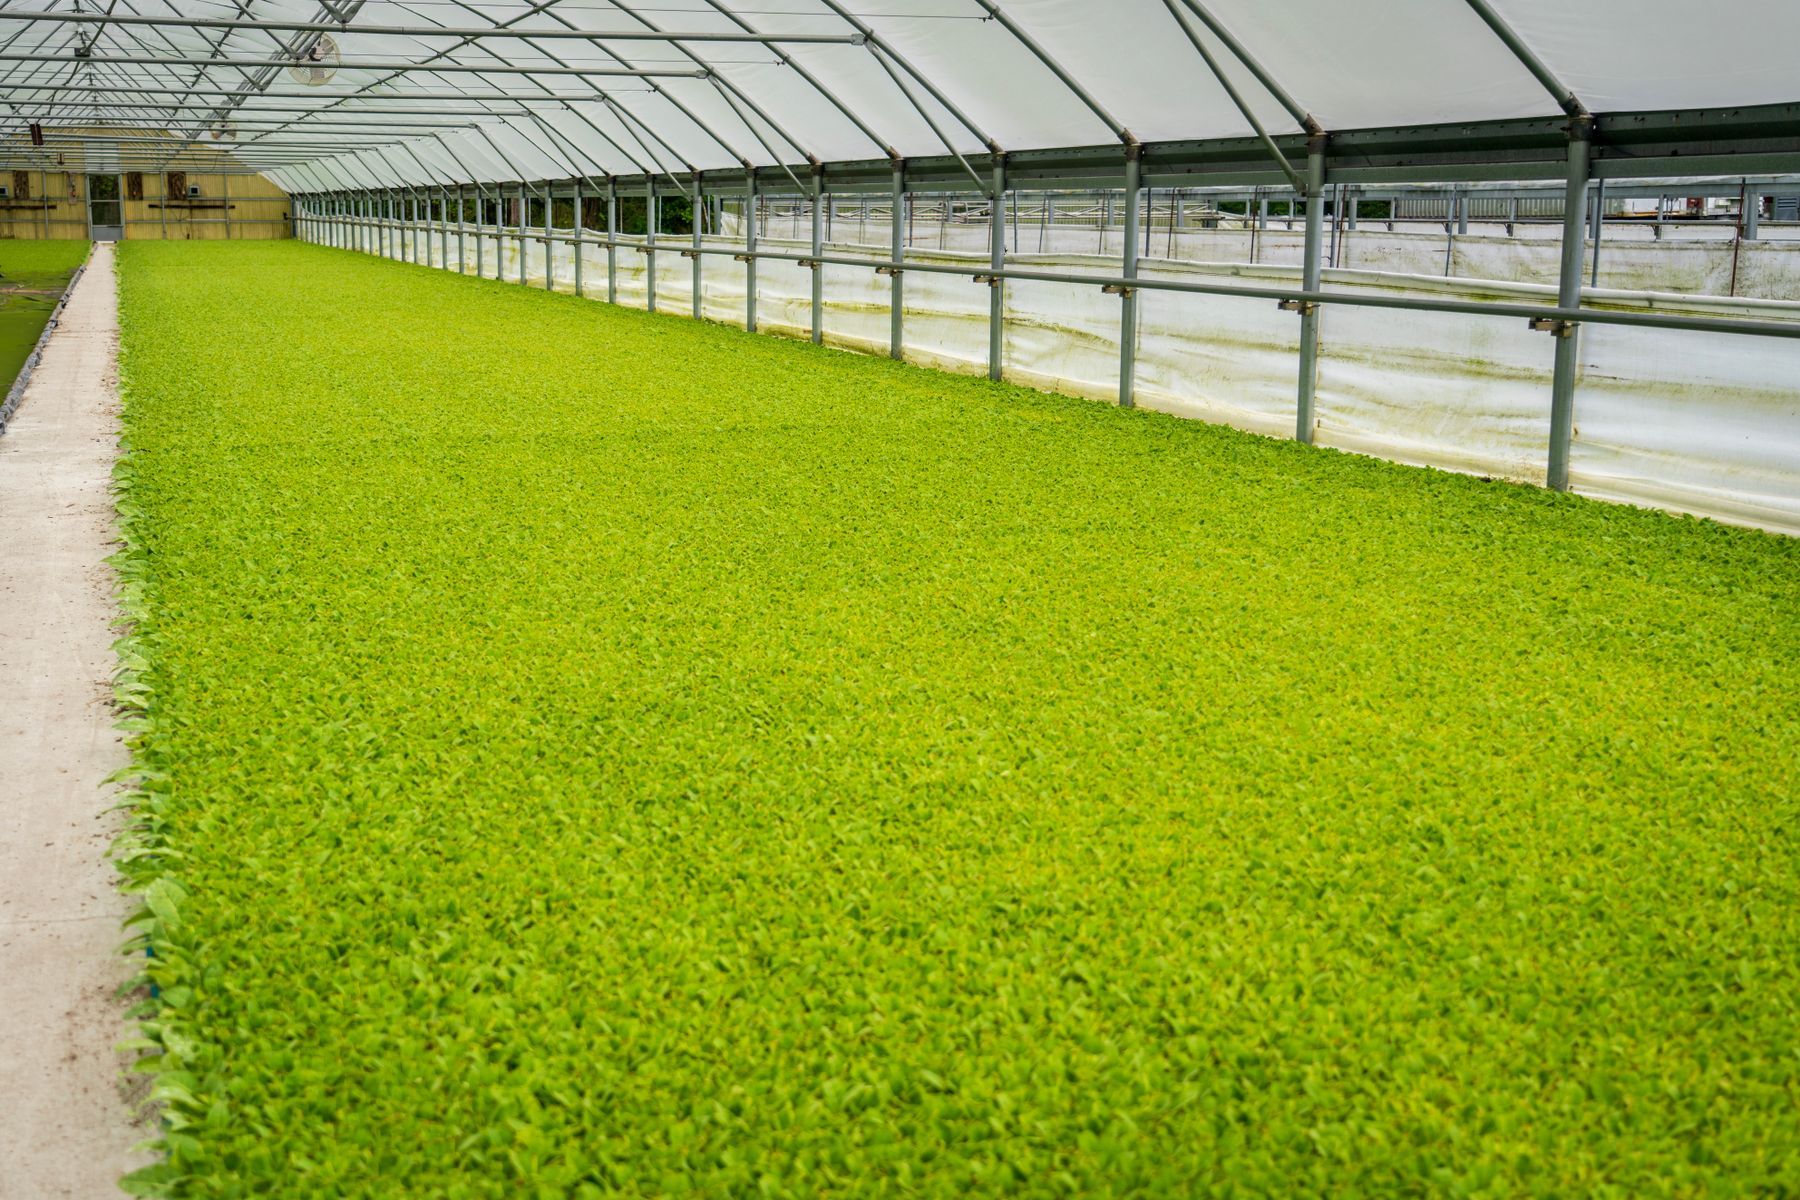
Long rows of plants inside a large commercial greenhouse

COMMERCIAL GROWERS. NURSERIES. PRODUCTION AGRICULTURE.

More locations.
More moving parts.
A closer review.

From nursery production and greenhouses to field crops, hay, storage and handling facilities.

I work with growers to understand the full operation: ownership entities, insured locations, production activities, storage, equipment and the points where property coverage and business exposures meet.

We’ll build the conversation around your current operation and the growth you’re planning.

WHERE YOUR REVIEW CAN GO DEEPER

Coverage with
the operation in view.

Expansion, equipment purchases, building improvements and changing inventory can make last year’s schedule a poor description of this year’s needs.

Large commercial building valuations

Review replacement-cost inputs for warehouses, packing and processing buildings, equipment shops, storage structures and other large facilities. Construction type, height, occupancy, attached systems and specialized improvements matter.

Greenhouses & nursery structures

Identify greenhouse types, coverings, heating, ventilation, irrigation and other installed systems. We’ll review how structures, equipment and plant inventory are treated under the available policies.

Equipment & seasonal inventory

Review machinery schedules and eligible stored hay, harvested crops, supplies and other inventory as values rise and fall. Where available, carrier-approved seasonal schedules can reflect changing exposures.

Business continuity questions

Discuss what happens if a covered loss disrupts a critical building, equipment item or storage location. We can review available business-income, equipment-breakdown, spoilage or other options where appropriate.

Liability, vehicles & multiple locations

Discuss products, premises, deliveries, commercial vehicles and the relationships between locations and entities. We’ll identify which exposures belong in a farm, commercial or separate coverage discussion.

KNOW WHAT THE LIMIT IS BASED ON

The size of the building
is only the beginning.

A generic square-foot estimate can overlook features that make your facility different. I look at the details behind the limit and the policy’s settlement provisions to help identify potential overinsurance, underinsurance and outdated assumptions.

See our building-valuation approach

THE OPERATION AND THE NEXT GENERATION

Protect what’s working.
Plan for what comes next.

Alongside your property review, we can discuss life insurance for family protection and legacy needs, including whether an indexed universal life policy fits your goals and long-term funding capacity.

Explore IUL, wealth & legacy planning

Coverage for stored commodities or plant inventory is not a promise of growing-crop yield or revenue protection. Availability varies by crop, property, carrier and policy. Tax and succession planning should be coordinated with your advisors.
Request a large-operation review

A GOOD CONVERSATION CHANGES THINGS

Let’s take a closer look
at your insurance.

A new property. A changing operation. A renewal that needs a second look.
Tell me what’s on your mind, and we’ll start there.